My husband earned 4 times what I did, yet he demanded we split every expense exactly 50/50. The night our washing machine broke, I spent an hour scrubbing his clothes by hand in the bathtub. Then my phone buzzed. Payment request: $1.94 — my half of the laundry detergent. I paid it without arguing. But that tiny request finally made me wonder where all my other money had been going. So after he fell asleep, I opened 5 years of bank statements.
My husband earned 4 times what I did, but he insisted our marriage should be strictly “50/50.”
He said it when I needed work shoes and asked him to cover groceries until payday. He said it when I couldn’t afford dinner with his colleagues.
And he said it when our washing machine broke.
I asked him to pay for the repair upfront and let me reimburse my half after payday.
“An emergency on your side doesn’t change our agreement, Lena.”
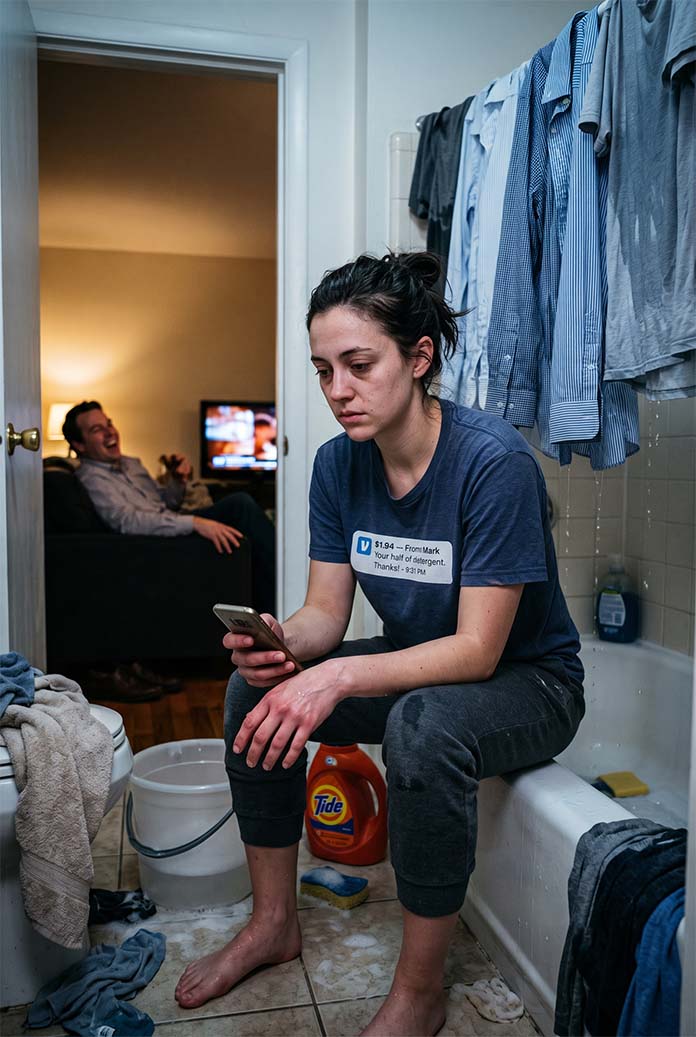
So I washed his clothes in the bathtub.
After almost an hour of scrubbing, my phone lit up.
Graham had requested $1.94.
Your half of the detergent.
I could hear him laughing at the television.
I paid it. Then I sat beneath his dripping shirts and finally understood that whatever he meant by equal, it had never included me.
When my father was dy:ing, Graham had seemed dependable. He brought groceries, handled phone calls, and helped me through paperwork.
“Let me handle the complicated parts.”
We married a few months after Dad’s funeral and moved into my childhood home.
I knew Dad had left it to me. Graham said I misunderstood the financial arrangements.
“There’s a maintenance trust and obligations attached to the property. Inheriting a house doesn’t mean living here is free.”
The required monthly payment, he said, was $1,900.
My half was $950.
He earned $136,000 a year before bonuses. I earned $34,000 as a classroom aide.
We spent according to his income and divided expenses as though our salaries matched. Eventually, groceries and other necessities went on my credit cards.
Graham called that a lesson in cash-flow management.
After the detergent request, I downloaded my bank statements.
There were 60 housing payments.
$57,000.
Every payment had gone to HB Residential Services.
I had assumed it was the trust’s property account. But a business filing identified Graham as the company’s sole member.
I opened a notebook.
What were these payments for?
Where was his half?
I was still writing at 2 a.m.
On Monday, the school secretary called my classroom. Someone from a title company needed me.
“I’m verifying the power of attorney submitted for the sale of your property on Willowbend Lane,” the woman explained.
“What sale?”
“The proposed closing is next Friday.”
“My house isn’t for sale.”
Her voice changed.
“Have you authorized your husband to sign documents on your behalf?”
“No.”
She placed the file on hold and gave me the company’s main number so I could verify the call independently.
I did.
After confirming my identity, they sent the relevant documents.
The purchase price was $512,000.
The power of attorney carried a signature that looked like mine.
I hadn’t signed it.
My coworker Rosa found me shaking in the staff bathroom.
“My husband is trying to sell my house,” I whispered.
“Go deal with it,” she said. “I’ll cover your classroom.”
At lunchtime, Graham texted.
Keep next Thursday free. An investor and his wife are coming for dinner. Buy ribeyes.
The buyer on the contract was Colin Drake.
Is the investor Colin? I asked.
Yes. Why?
Just checking.
He expected me to buy dinner for the man purchasing my home.
Dad’s workshop stood behind the house. Graham wanted to demolish it. Refusing him had been one of the few arguments I hadn’t surrendered.
I had barely entered since the funeral, but Dad always kept copies.
Inside his filing cabinet was a folder labeled HOUSE—LENA.
It contained his estate plan, the maintenance trust agreement, and a letter.
Lena,
The house is paid for. My estate plan leaves it to you.
The separate maintenance trust will cover property taxes, insurance, and necessary repairs. Whatever remains will be distributed to you when you turn 30.
You’ll still have ordinary bills. But you should never have to pay anyone for permission to live in your own house.
Keep the records. Ask questions.
Love,
Dad
My 30th birthday was 7 months away.
For 5 years, Graham had described my inheritance as a burden he was helping me carry.
I called the attorney named in the documents.
Martin Ellison met me the following morning. From his estate file, he produced the recorded ownership documents and confirmed the current title.
“The house passed to you outright. There’s no mortgage explaining those payments.”
Then he showed me something else.
My nomination of Graham as successor trustee after Dad’s accountant retired.
That signature was real.
I remembered Graham placing the form beside my dinner plate.
“This just means I can handle the house account.”
“I signed it,” I said.
“You appointed him to a job with obligations,” Martin replied. “You didn’t give him the money.”
The trust had started with $225,000. Graham was required to provide annual accountings.
I had never seen one.
“I thought his spreadsheets were the accounting.”
“Those show what he charged you. They don’t show what happened to the trust.”
Martin helped me formally dispute the sale and the purported power of attorney. The title company confirmed the closing would not proceed while Graham’s authority was disputed.
I stayed with Rosa, redirected my paycheck, secured my email, and gathered records.
Martin brought in a litigation attorney and a forensic accountant, Priya Shah.
Over the following week, requests supported by my trust documents and verified identity produced preliminary bank statements. Complete tracing would take longer.
I also copied property invoices from the shared household folder on our computer.
The trust held a little over $31,000.
Some withdrawals covered genuine taxes, insurance, and repairs.
Others went to Graham’s company for work that hadn’t happened.
A $12,600 heating and cooling system.
Drainage improvements.
Replacement appliances.
Our upstairs bedroom was still unbearable in summer. Our broken refrigerator had been sitting unused for 4 months because Graham refused to replace it until I had my $800.
That same month, he had spent $1,400 on a golf weekend.
Priya compared the invoices with my household bills.
Some expenses had been charged to the trust and then charged to me again.
“Does this prove where the money went?” I asked.
“It tells us which transactions to investigate,” she said. “We still need the receiving account records.”
Graham knew the sale was blocked. He treated it as an inconvenience.
“You confused the title company,” he told me.
“I told them I hadn’t agreed to sell.”
“We’ll straighten everything out at dinner.”
Colin later forwarded Graham’s email assuring him that I had simply become confused during verification.
Graham expected me to retreat when he corrected me in front of someone else.
This time, I asked Martin to attend.
The legal work was already underway. Dinner wasn’t going to decide whether I kept my home.
It was where I would finally speak for myself.
Colin and his wife, Elise, arrived just before 7.
Graham poured wine.
“We should clear up the title issue,” Colin said.
“A misunderstanding.” Graham rested his hand on my chair. “Lena gets overwhelmed by legal matters.”
I moved my chair forward.
“I was overwhelmed when a stranger told me my house was being sold.”
Colin turned toward him.
“You said she agreed.”
“She did.”
“No,” I said. “I didn’t.”
The doorbell rang.
When Martin entered, Graham stopped smiling.
“You hired an attorney?”
“Yes.”
“With what money?”
Everyone went quiet.
Martin placed a folder on the table.
“Your wife disputes the transaction and the authorization submitted for it. There will be no closing tomorrow.”
Colin took out his phone.
“You emailed me that she had signed everything. I paid earnest money.”
“This is getting blown out of proportion,” Graham said.
Elise picked up her purse.
At the door, Colin apologized.
“Graham showed us through while you were working. He said you preferred not to deal with the sale.”
I remembered the afternoons Graham claimed contractors were visiting.
“I understand,” I told Colin.
I knew how convincing my husband could be.
After they left, Graham turned on me.
“That man could have brought millions in business to my firm.”
“You offered him my house.”
“Our house.”
“You submitted a power of attorney because your name wasn’t on the deed.”
I placed Dad’s letter beside the invoices.
“What were my $950 payments for?”
“Taxes. Insurance. Management.”
“The trust paid the taxes and insurance.”
“There were other costs.”
“Show me.”
“You wouldn’t understand the records.”
“Priya Shah will.”
“Who?”
“The forensic accountant.”
That was when he looked frightened.
I pushed the heating and cooling invoice toward him.
“Where is this system?”
“I moved money around. That’s what managing assets involves.”
“Into your company?”
“For efficiency.”
“And the house sale proceeds?”
Martin opened the proposed disbursement instructions from the closing file.
The seller’s money was directed to HB Residential Services.
“I was going to invest it,” Graham said.
“You were selling the house I sleep in. Why didn’t you ask?”
“Because you’re sentimental about everything your father touched.”
He had known my answer. He had decided it didn’t matter.
I handed him the accounting I had prepared: housing payments, disputed repair charges, and my debts listed separately.
At the bottom, I had written:
Laundry detergent: $1.94.
He stared at it.
“You’re doing all this over detergent?”
“No. That was when I finally started looking.”
“I’ve carried you for 5 years.”
“You lived in my house, controlled my inheritance, and collected payments you can’t explain while I went into debt.”
“I made us comfortable.”
“Our refrigerator doesn’t work.”
For once, he had no answer.
Martin told him to preserve all records and obtain his own counsel.
Graham asked whether I was divorcing him.
“Yes.”
He packed a suitcase and chose to leave for a hotel.
At the door, he looked back.
“You have no idea what things cost without me.”
“I’m going to find out.”
Rosa came over afterward.
She found me taking my favorite tea from behind the baking pans. Then I retrieved the crackers I hid so Graham wouldn’t count them in his grocery calculations.
She placed the tea at the front of the shelf.
“Here?”
I nodded and began to cry.
Later, we ordered sandwiches.
When I reached for my phone to send her half, she shook her head.
“You can buy next time.”
I had forgotten people could say that and mean it.
The divorce took 14 months.
Bank records eventually traced trust money through Graham’s company into travel, luxury purchases, and a car down payment. Priya separated every legitimate expense she could verify.
There was no matching series of $950 contributions from Graham.
The “50/50” housing payment had existed only on my side.
During the dispute, he produced annual accountings bearing signatures that supposedly acknowledged my approval.
I denied signing them. The preparer confirmed Graham had supplied the signed pages, and investigators examined them alongside the purported power of attorney.
Emails also explained the sudden house sale.
Graham knew my approaching 30th birthday would require a final trust distribution and an accounting. Much of the money was already gone.
The house was the next asset he intended to control.
His explanations changed from rent to voluntary contributions to management fees.
There was no agreement supporting any of them.
We didn’t recover everything. But the settlement, funded partly through the sale of his assets, cleared my credit-card debt and restored a substantial portion of the diverted money.
The house stayed mine. A replacement trustee handled the remaining funds and the distribution due at my birthday.
Graham lost his job after his employer reviewed his use of business accounts.
The cri:minal case took longer. In his eventual plea, he admitted diverting trust funds and knowingly submitting documents with fal:se signatures. Restitution accounted for money already recovered.
By then, I was spending less time thinking about his consequences and more time rebuilding my life.
I bought a basic refrigerator a few weeks after he left, with payments I could manage.
Then I repaired the washing machine and replaced the leaking faucet.
I kept my school job. I stopped skipping lunch to cover credit-card minimums.
For months, I still saved every receipt.
One afternoon, I threw away a coffee receipt and waited for the familiar guilt.
No notification came.
I went back to work.
After the divorce, I cleaned Dad’s workshop and framed his letter above a small desk. Through a community organization, a financial counselor began holding occasional appointments there.
I helped organize paperwork and connect women with qualified advice.
Sometimes someone apologized before opening her folder.
“This might be nothing.”
“Then we can look,” I said. “You’re allowed to understand your own money.”
One evening, after the last appointment, I went inside and started the laundry.
Only mine.
I made dinner and put the leftovers in a refrigerator that worked.
There were still bills. The house still needed repairs. I still made mistakes.
But I read what I signed.
I knew what my accounts held.
I bought tea without hiding it.
When the dryer stopped, I folded my clothes on the table where Graham had spent years explaining why fairness required me to struggle.
Then I put the last shirt away.
There was no payment request waiting on my phone.
The house was quiet, and I was comfortable.
I no longer felt the need to apologize for either.